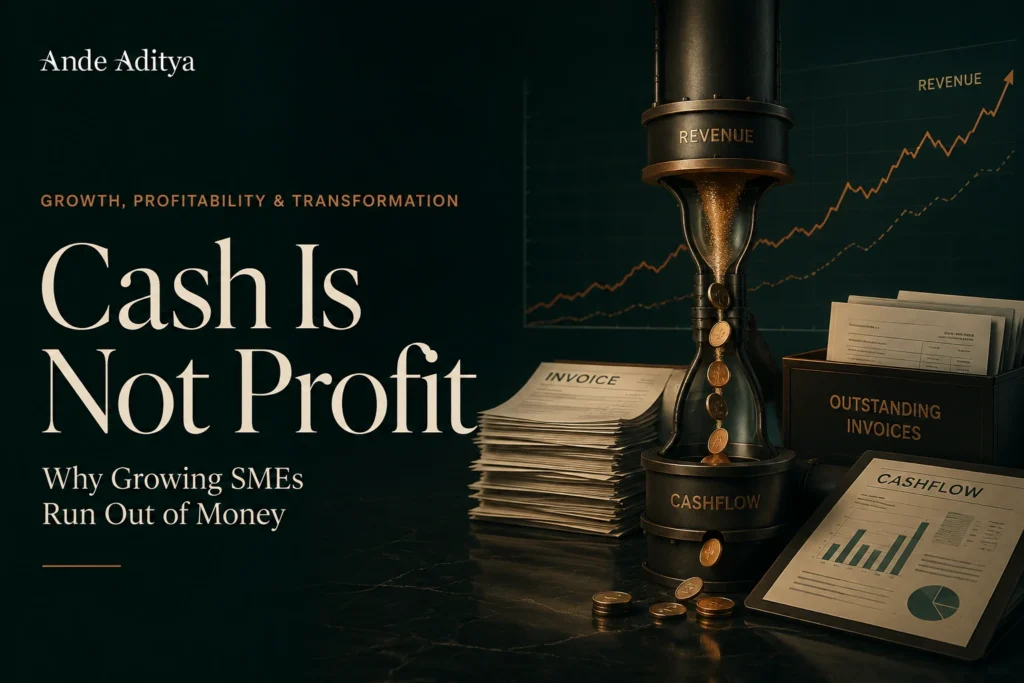
One of the most dangerous sentences in a growing business is: “We are profitable, so why are we short of cash?”
Profit and cash are connected, but they are not the same thing. A company can report a healthy margin and still struggle to pay salaries, suppliers, taxes or expansion costs because the cash is sitting somewhere else—in receivables, inventory, deposits, new equipment or projects that have not yet converted into collections.
Growth often makes this problem worse before it makes it better. More sales can mean more stock, more staff, larger credit exposure and bigger working-capital requirements. The P&L looks stronger while the bank balance becomes tighter.
This is why I treat cash flow as an operating discipline, not simply an accounting output.
Where cash disappears in a growing company
Receivables grow faster than collections
Revenue is recognised when a sale is made, but cash arrives later. If customers take 60 or 90 days to pay while suppliers require faster payment, growth creates a financing gap.
Inventory expands ahead of demand
Businesses often buy more stock to avoid shortages or secure better pricing. The margin may look attractive, but cash becomes trapped on the shelf.
Expansion costs arrive before expansion revenue
New hires, premises, technology, marketing, deposits and market-entry costs must often be funded months before the new activity generates reliable cash.
Tax and statutory payments do not wait for customer collections
A company can appear profitable but still face a liquidity squeeze because cash outflows have a fixed timetable while collections do not.
The cash conversion cycle matters more than many owners realise
The cash conversion cycle is a simple way to think about how long money remains tied up between paying suppliers and collecting from customers. The longer the cycle, the more working capital growth requires.
Owners do not need a finance textbook to manage this. They need visibility into three numbers: how quickly customers pay, how long inventory sits and how much time suppliers allow before payment.
When those three numbers deteriorate, revenue growth can become cash-negative. This is particularly relevant when external finance is more selective or expensive. OECD’s 2026 work on SME finance continues to highlight financing conditions and the need for broader funding options amid economic uncertainty.
Five owner-level actions
1. Forecast cash weekly, not only monthly
A rolling 13-week cash forecast creates earlier visibility and makes action possible before the problem becomes urgent.
2. Manage receivables commercially
Collections are not only a finance task. Sales teams should understand payment terms, credit quality and overdue exposure.
3. Challenge inventory assumptions
Ask why stock is being held, how quickly it moves and which items are consuming cash without supporting margin.
4. Match growth speed to funding capacity
Not every growth opportunity should be accepted at once. Growth that cannot be financed can damage a good business.
5. Separate profit improvement from liquidity improvement
Margin actions and cash actions overlap, but they are not identical. Track both deliberately.
When owners should consider external capital
External financing can be useful when the underlying economics are sound and the capital has a clear purpose. It becomes dangerous when new debt is used to hide structural cash-flow problems.
Before raising capital, understand whether the need comes from growth, timing, poor collections, excess inventory, weak margins or recurring operating losses. Different problems require different solutions.
This is also why financing readiness starts with the business model and cash logic—not with the pitch deck.
Cash creates optionality
A business with good cash discipline can negotiate from strength, move faster when opportunities appear and survive surprises without desperate decisions.
Profitability tells you whether the model can create value. Cash tells you whether the business can keep operating long enough to realise it. Owners need both.
Related on AndeAditya.com: Business Support • About Ande • Private Conversation
One trusted senior relationship across business and selected owner priorities.